Protect Your Bank Account Using Disposable Virtual Credit Cards for Free Trials and Safety
Signing up for a new streaming service, a professional software trial, or a niche fitness app often feels like a gamble. You want to see if the service provides value, but the requirement to enter your primary credit card information creates immediate friction. The fear isn't just about the service itself; it is about the forgotten subscription that turns into a recurring charge three months down the line because the cancellation process was intentionally buried in the settings.
Beyond the annoyance of unwanted subscriptions, there is the escalating risk of data breaches. Every time you share your real card details with a new merchant, you expand your digital footprint and increase the chance of your financial data ending up on a leaked database. This is where disposable virtual credit cards become a game-changer for savvy internet users. They act as a protective layer between your actual bank balance and the companies trying to access it.
Related posts
Instant Virtual Credit Card Approval Even with Bad Credit: Fast Online Access
Waiting weeks for a physical piece of plastic to arrive in the mail is a relic of the...
Read more →
Automating Corporate Spend with API-Integrated Virtual Credit Cards
Modern finance departments face a mounting stack of recurring invoices, SaaS subscriptions, and ad-hoc vendor payments. Managing these...
Read more →
Temporary Virtual Credit Card Number Generators for Privacy: Stopping Data Breaches and Tracking
Handing over your primary credit card details to every website you visit is like giving a stranger a...
Read more →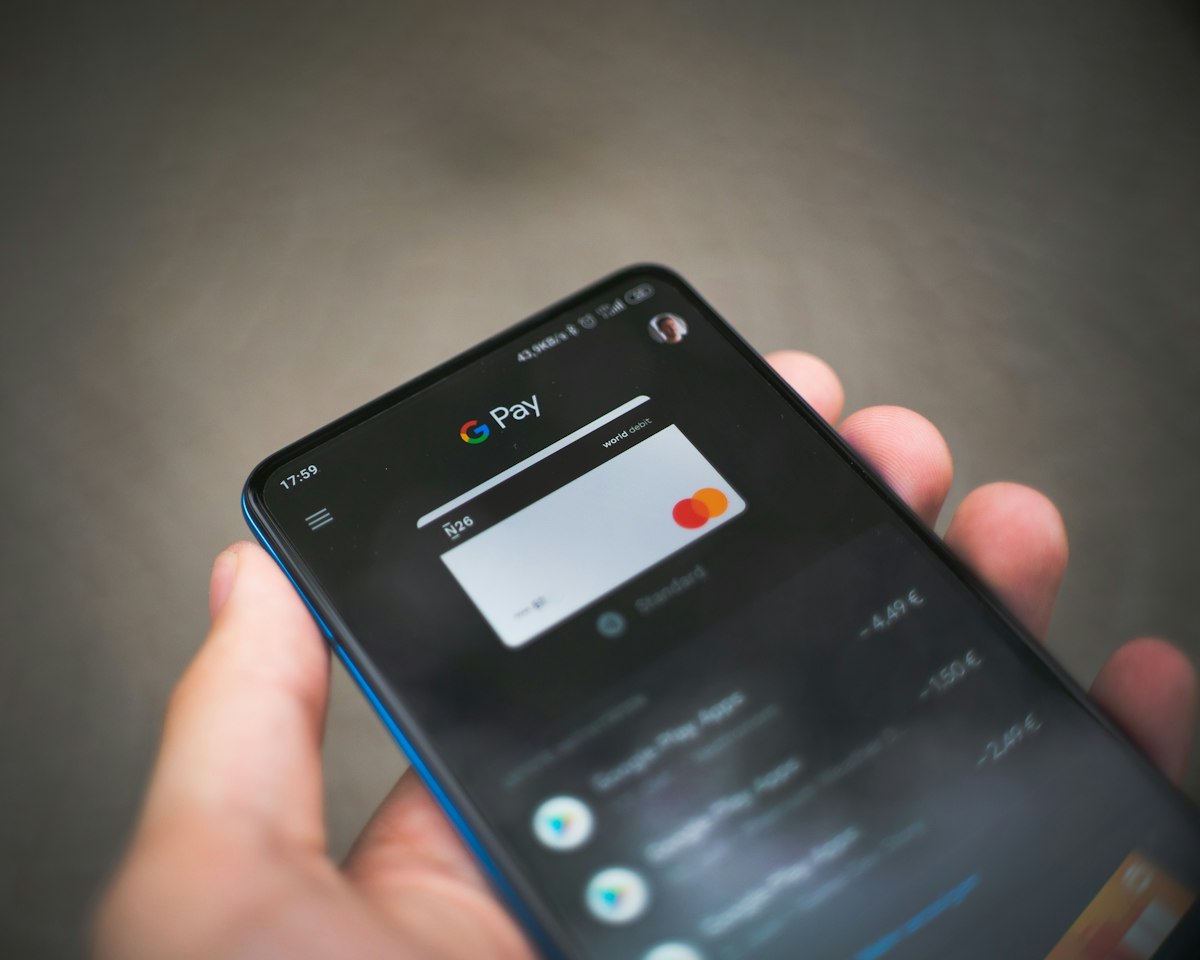
Immediate Access: Exploring Digital Bank Credit Cards with Instant Issuance
The landscape of personal finance is rapidly evolving, and nowhere is this more evident than in how we...
Read more →This article explains how these digital payment tools work, why they are the most effective way to manage free trials, and how they significantly boost your online security. We will look at the practical differences between various types of virtual cards and how you can start using them to take back control of your financial privacy without spending a dime in extra fees.
Key takeaways
- Prevent unwanted charges: Use single-use cards that automatically decline once a trial period ends or a specific limit is reached.
- Enhanced data security: Keep your primary bank or credit card numbers hidden from merchants, reducing the impact of potential database leaks.
- Granular spending control: Set hard limits on specific cards to ensure a company can never charge you more than the agreed-upon price.
- Easy management: Close or pause virtual cards instantly through an app without affecting your physical credit card or bank account.
How Disposable Virtual Credit Cards Work
A virtual credit card (VCC) is a unique 16-digit card number, CVV code, and expiration date that is generated digitally. It is linked to your actual funding source—like a debit card or bank account—but it functions as a proxy. When you use a VCC, the merchant never sees your real financial information. They only see the temporary data provided by the virtual card issuer.
The "disposable" aspect takes this a step further. These are often referred to as burner cards. Once a transaction is processed, or once a specific time limit expires, the card number becomes invalid. If a hacker steals that card number from the merchant's database a month later, they will find a dead card with zero value. This architecture makes them the perfect tool for one-time purchases or testing out new services.
Single-Use vs. Merchant-Locked Cards
Not all virtual cards are identical. Most providers offer two main types: single-use and merchant-locked. Single-use cards vanish the moment they are used once. These are ideal for buying a gift from an unfamiliar website. Merchant-locked cards, on the other hand, stay active but can only be used with the first merchant where they were authorized. If you use a merchant-locked card for a Netflix trial, that card will work for Netflix every month, but it will be declined if someone tries to use it at Amazon.
The Best Way to Handle Free Trials
The business model for many modern SaaS companies relies on "dark patterns"—design choices that make it easy to sign up but difficult to cancel. They hope you will forget about the 7-day trial so they can bill you for a full year. Using a disposable virtual credit card flips the script. You can create a card, set a total spending limit of $1, and use it to sign up for the trial.
When the company attempts to charge you $99 at the end of the week, the transaction will fail because the card doesn't have the funds or has already been closed. You get to enjoy the trial period without the anxiety of a surprise bill. It forces the company to reach out to you if they want your business, rather than them silently taking money from your pocket.
Avoiding the Subscription Trap
Subscription fatigue is a real problem. Between news sites, entertainment, and software, it is easy to lose track of where your money is going. By using a different virtual card for every subscription, you can see exactly who is charging you and how much. If a service makes it too hard to cancel through their website, you don't have to argue with customer support. You can simply "pause" or "delete" the card in your VCC dashboard, and the payments stop instantly.
Boosting Your Online Safety and Privacy
Data breaches are no longer a matter of "if," but "when." Even major corporations have fallen victim to sophisticated hacks. When you use your real credit card at twenty different online stores, you have twenty points of failure. If even one of those stores has poor security, your card details are compromised, and you have to go through the hassle of calling your bank, canceling your card, and waiting for a new one in the mail.
Virtual cards eliminate this headache. Since the card is digital and often disposable, the risk is contained. If a site you bought a t-shirt from two years ago gets hacked, the virtual card you used is likely already expired or closed. Your main bank account remains untouched and invisible to the attackers.
Protecting Your Identity
Privacy is another significant factor. Some virtual card providers allow you to use any name or address for the billing information, provided the transaction is authorized. This adds a layer of anonymity when you are dealing with platforms where you might not want to share your full legal identity. While you must still follow the law and the provider's terms of service, this feature is a powerful tool for those concerned about their digital shadow.
Choosing a Virtual Card Provider
When looking for a provider, you should consider several factors including fees, ease of use, and compatibility. Many fintech banks and dedicated privacy startups offer these services for free or for a small monthly subscription. You should look for a provider that offers a mobile app for quick card generation and a browser extension that can auto-fill the virtual card details at checkout.
Check if the provider allows for "zero-dollar" authorizations. Some services will ping a card for $0.00 or $1.00 just to see if it is valid before starting a free trial. A good virtual card provider will handle these pings correctly. Also, ensure the provider is transparent about how they make money; usually, they take a small cut of the interchange fee paid by the merchant, meaning the service is often free for the consumer.
Potential Limitations to Keep in Mind
While disposable virtual credit cards are incredibly useful, they aren't a universal solution for every single transaction. Some merchants have started blocking known virtual card ranges to prevent trial abuse. If a website tells you that your card is "not accepted," it might be because they have flagged the issuer as a virtual card provider.
Additionally, handling returns can be slightly more complex. If you use a single-use card and then need a refund, the money usually still makes it back to your primary account, but it can take a few extra days for the provider to route the funds correctly. For large purchases where you expect you might need a refund, a merchant-locked card is often a better choice than a strictly disposable one.
Frequently Asked Questions
Are disposable virtual credit cards legal to use?
Yes, virtual credit cards are perfectly legal. They are a legitimate financial technology used to enhance security and privacy. They are issued by licensed financial institutions and follow the same regulations as traditional physical cards. However, using them to bypass regional pricing or to commit fraud is still a violation of most merchants' terms of service.
Do these cards affect my credit score?
Generally, no. Most virtual card providers do not perform a hard credit pull when you sign up, as they are usually linked to your existing debit card or bank account. Since they are not traditional credit lines, using them or closing them frequently has no impact on your credit history or score.
Can I use virtual cards for physical in-store purchases?
Most disposable virtual cards are designed for online use. However, some providers allow you to add your virtual card to digital wallets like Apple Pay or Google Pay. If the card is added to a mobile wallet, you can use it at any physical store that accepts contactless payments, although this is less common for "disposable" single-use numbers.
What happens if a merchant tries to charge a closed card?
The transaction will simply be declined. The merchant will receive a notification that the payment failed, just as if you had insufficient funds or an expired card. They will usually email you asking for an updated payment method. This is exactly why they are so effective for stopping unwanted subscriptions.
Is there a limit to how many cards I can create?
This depends entirely on the provider. Some free tiers allow you to create a few new cards per month, while premium plans might offer unlimited card generation. For the average user, even a basic plan usually provides enough cards to cover all their major subscriptions and occasional one-off trials.
Conclusion
Disposable virtual credit cards are one of the most effective tools available for maintaining financial sanity in a world of endless subscriptions and frequent data breaches. They offer a simple, proactive way to protect your money and your privacy. By using these cards for free trials and shopping on unfamiliar websites, you eliminate the risk of hidden fees and ensure that a single security lapse at a retail store doesn't compromise your entire bank account.
Taking five minutes to set up a virtual card account today can save you hours of frustration and potentially hundreds of dollars in the future. In an era where your data is constantly under threat, adding this layer of insulation is a smart, practical move for anyone who spends time online.