Instant Credit Card Access: Get Approved and Start Spending Today
Waiting two weeks for a piece of plastic to arrive in the mail feels like a relic of a slower era. When you find a limited-time travel deal or face an unexpected emergency repair, the traditional timeline for credit simply does not work. You need a solution that matches the speed of your digital life, providing purchasing power the moment you are approved.
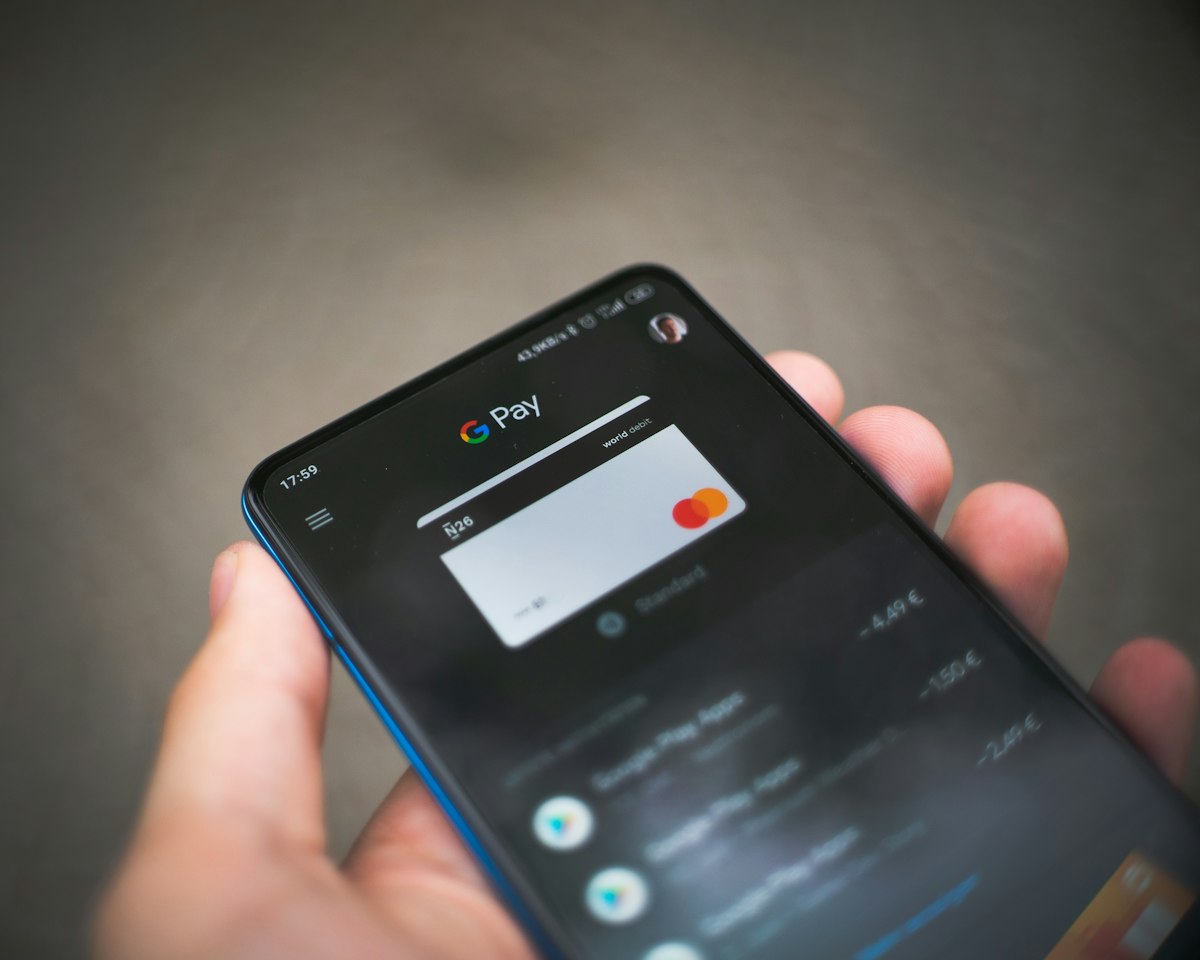
The rise of the instant credit card has changed the way consumers manage their finances. No longer is the application process a black box of manual reviews and paper trails. Today, sophisticated algorithms can assess your creditworthiness in seconds, offering a decision almost as fast as you can click the submit button. This shift is about more than just speed; it is about immediate utility through virtual card numbers and mobile wallet integration.
Related posts
Maximizing Control and Cash Flow with a Corporate Card Strategy
If your finance team is still chasing down paper receipts at the end of every month, you are...
Read more →
Establishing Business Credit with a Secured Card Strategy
Traditional lenders often operate on a "have money to get money" philosophy that leaves many entrepreneurs in the...
Read more →
Smart Strategies for Using Balance Transfer Cards to Eliminate Debt
High-interest credit card debt often feels like running on a treadmill that keeps getting faster. You make your...
Read more →How to Use 0 Balance Transfer Credit Cards to Erase High-Interest Debt
You are likely staring at your monthly credit card statement and feeling a sense of dread. When the...
Read more →In this discussion, we will break down how these rapid-approval systems work and how you can access your new account before the physical card ever hits your mailbox. We will also look at the different types of cards available, from retail-specific options to premium rewards cards, and what you need to prepare to ensure your application goes through smoothly.
Managing your expectations is key. While many companies promise a fast decision, not every card allows for immediate spending. We will clarify the distinction between instant approval and instant use, helping you choose the right financial tool for your specific situation without falling into common traps that could impact your credit health.
Key takeaways
- Instant approval refers to the speed of the decision, while instant use allows you to access a virtual card number immediately.
- Automated underwriting systems use your credit report and income data to make split-second lending decisions.
- Retail store cards and certain major bank cards are the most likely to offer immediate access via mobile wallets like Apple Pay or Google Pay.
- Preparation is essential; having your financial documentation ready and checking your credit score beforehand increases your chances of a seamless experience.
The Difference Between Instant Approval and Instant Use
It is easy to get these two terms confused, but understanding the distinction is important for your financial planning. Instant approval means that the bank's automated system has reviewed your application and granted you a line of credit within seconds. You will know your credit limit and your interest rate right away, but you might still have to wait for the physical card to arrive to make a purchase.
Instant use, or instant credit card access, goes a step further. Once approved, the lender provides you with a virtual card number, expiration date, and CVV code through their secure mobile app or website. You can then manually enter these details for online shopping or add the card to your digital wallet for in-store purchases using NFC technology. This feature is the gold standard for those who need to spend money immediately.
How Automated Underwriting Works
How does a bank decide to lend you thousands of dollars in less than 60 seconds? The answer lies in automated underwriting. When you submit your application, the lender's system triggers a "hard pull" on your credit report from one of the major bureaus. The algorithm scans for specific data points, such as your payment history, current debt levels, and the age of your accounts.
In addition to your credit report, the system looks at the information you provided about your annual income and employment status. By comparing these factors against their internal risk models, the software determines if you meet the criteria for the card. If your profile is straightforward and meets all the benchmarks, the system issues an approval. If there are inconsistencies or if your credit history is thin, the application may be flagged for manual review, which can take several days.
The Role of Soft vs. Hard Credit Pulls
Many modern lenders now offer a "pre-qualification" step. This uses a soft credit pull, which does not affect your credit score, to give you an idea of your approval odds. While this isn't a guarantee, it is a helpful way to filter out cards you likely won't get. Once you officially apply for the instant credit card, a hard pull is performed, which may cause a temporary dip of a few points in your credit score.
Types of Instant Credit Cards Available
Not all cards are created equal when it comes to speed. Depending on your credit profile and your spending needs, you might find one category more accessible than others. Each has its own set of pros and cons regarding fees, interest rates, and rewards.
Retail and Store Credit Cards
Store cards are among the most common sources of instant credit. If you have ever been offered a discount at a checkout counter for opening an account, you have seen this in action. These cards often have lower credit score requirements than general-purpose cards. The primary benefit is that you can use the credit line immediately at that specific retailer. However, be cautious: store cards frequently carry much higher interest rates than traditional bank cards.
General Purpose Rewards Cards
Major banks have started competing in the instant access space. Some of the top travel and cashback cards now offer virtual card numbers upon approval. These are highly versatile because you can use them anywhere that accepts major payment networks. These cards usually require a good to excellent credit score but offer significantly better perks, such as sign-up bonuses and travel insurance.
Secured Cards for Credit Building
If you are working with a limited or damaged credit history, a secured instant credit card might be your best path. These require a refundable security deposit that usually acts as your credit limit. Because the risk to the lender is lower, approval is often very fast. While you might not get a virtual number for every secured card, they are an effective way to start the approval process immediately and begin rebuilding your score.
Preparing Your Application for Success
To ensure the fastest possible decision, you should have all your information ready before you start the form. Any discrepancy can cause the system to pause and move your application to a manual queue. Accuracy is your best friend when you are looking for speed.
You will need your legal name, current address, Social Security number, and a detailed account of your gross annual income. Some lenders may also ask for your monthly housing payment. If you are applying via a mobile app, ensure your internet connection is stable. A timed-out connection in the middle of an application can lead to errors that delay your approval by days.
Common Pitfalls to Avoid
The convenience of an instant credit card can sometimes lead to impulsive financial decisions. One major risk is applying for multiple cards in a short period. Each hard inquiry stays on your credit report for two years, and several inquiries in a row can signal to lenders that you are in financial distress, leading to denials.
Another trap is the high interest rates often associated with cards that offer easy, instant approval—especially store cards. If you cannot pay off the balance in full each month, the interest charges can quickly outweigh any initial discount or rewards you earned. Always read the fine print regarding the APR and any annual fees before you click the final "accept" button.
Security Features of Virtual Cards
One of the best aspects of instant credit card access is the enhanced security of virtual numbers. When a bank gives you immediate access, they often generate a temporary or digital-only card number. This number is separate from the one that will be printed on your physical card. If that digital number is ever compromised in a data breach, it is much easier to cancel and replace without affecting your entire account.
Furthermore, using these cards through a mobile wallet adds a layer of encryption known as tokenization. Your actual card details are never shared with the merchant during the transaction. This makes instant-use cards not only faster but often safer for online shopping than using a traditional physical card.
Frequently Asked Questions
Can I use my instant credit card for an ATM withdrawal right away?
Generally, no. While many cards allow for immediate online or mobile wallet purchases, cash advances usually require the physical card and a PIN that is sent separately through the mail. Additionally, cash advances often incur high fees and immediate interest, so they should be used sparingly.
Does 'instant approval' mean I am guaranteed to get the card?
No, instant approval is not a guarantee. It simply means the decision process is automated. You can still be denied if you do not meet the lender's specific criteria for income, credit score, or debt-to-income ratio. If you are denied, the lender is legally required to send you an "adverse action" notice explaining why.
What credit score do I need for an instant card?
The required score varies by card type. Retail store cards may accept scores in the "fair" range (580-669), while premium rewards cards from major banks typically require a "good" to "excellent" score (670 or higher). Secured cards are available for those with poor credit or no credit history at all.
Will getting an instant credit card hurt my credit score?
The application process involves a hard credit inquiry, which can cause a small, temporary drop in your score. However, in the long run, adding a new line of credit can help your score by improving your credit utilization ratio, provided you make your payments on time and keep your balances low.
How do I add my new card to my phone if I don't have the plastic yet?
Most lenders that offer instant use will have a button inside their official mobile app labeled "Add to Wallet." Once you tap this, the app securely communicates with your phone's operating system to link the account. You will not need to type in the numbers manually in most cases.
Conclusion
The transition toward instant credit card access is a win for consumers who value efficiency and security. By removing the long wait times associated with traditional banking, these tools allow you to manage your finances with greater agility. Whether you are looking to capitalize on a flash sale or need to cover an urgent expense, the ability to apply and spend within minutes is a powerful advantage.
However, the speed of the process does not diminish the responsibility that comes with new credit. It is essential to choose a card that aligns with your long-term financial goals, offers competitive rates, and provides the specific features you need. By doing your research and preparing your data beforehand, you can enjoy the benefits of modern lending without the usual stress of waiting for the mail.