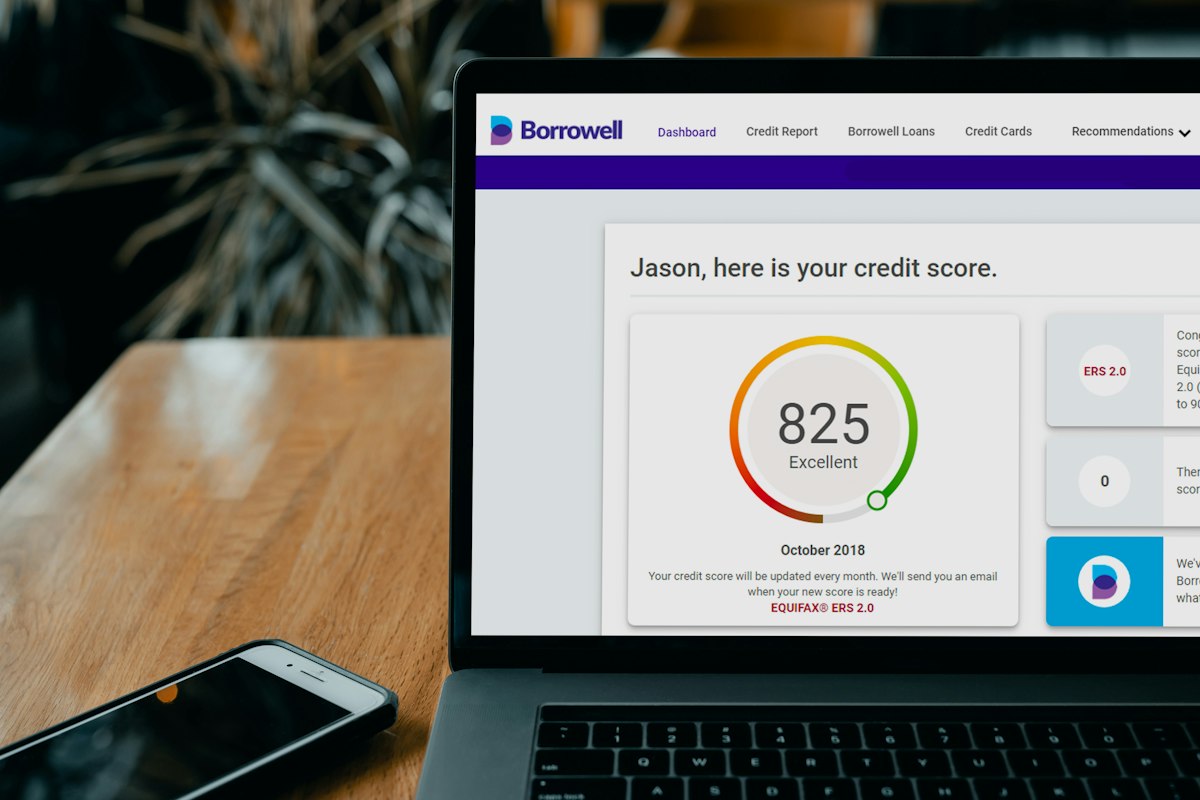
Credit Building Cards That Report to All Major Bureaus
Staring at a low credit score or a completely blank credit history feels like being locked out of a party everyone else is attending. Whether you are recovering from a financial misstep or just starting out, the path to better interest rates and higher loan approvals depends on one thing: your credit report. But here is the catch that many people miss. Not every credit card actually helps you build credit everywhere.
Some entry-level cards only report your activity to one or two of the major credit bureaus. If a future lender pulls a report from the one bureau your card ignores, it is as if your months of perfect payments never happened. To make real progress, you need a card that talks to Equifax, Experian, and TransUnion simultaneously. This ensures your hard work is reflected across the entire financial ecosystem.
Related posts
Fast-Graduating Secured Cards: Build Credit and Get Your Deposit Back Quickly
Putting down a cash deposit to secure a credit card is a smart way to establish or rebuild...
Read more →
Credit Card Options to Consider After Bankruptcy
Filing for bankruptcy can feel like a heavy door slamming shut on your financial life. The immediate aftermath...
Read more →
Subprime Credit Card Upgrading Options to Unsecured Status
Securing a credit card when your credit history is less than perfect often means starting with a subprime...
Read more →
Demystifying Deposit-Backed Credit Builder Cards for Absolute Beginners
Starting your financial journey can feel like a trap. You need a solid credit history to get approved...
Read more →In this discussion, we will break down the specific types of cards that prioritize triple-bureau reporting. We will look at the difference between secured and unsecured options, the hidden fees that can drain your progress, and how to manage these accounts to maximize your score growth. Choosing the right tool is the first step toward a more stable financial future.
Key takeaways
- Triple-bureau reporting ensures your credit history is visible to any lender, regardless of which credit report they pull.
- Secured cards are often the most accessible starting point, requiring a refundable deposit that acts as your credit limit.
- Look for cards with no annual fees and a clear path to "graduate" to an unsecured account over time.
- Consistent, on-time payments and low balance utilization are the two most influential factors in seeing your score rise.
The Importance of Triple-Bureau Reporting
Why does it matter if a card reports to all three bureaus? In the United States, there is no single "master" credit score. Instead, Equifax, Experian, and TransUnion each maintain their own file on you. When you apply for a mortgage, an auto loan, or even a new apartment, the lender might check only one of these reports. If your positive payment history is missing from that specific report, you could be denied or hit with a much higher interest rate.
By choosing credit building cards that report to all major bureaus, you are essentially triple-stamping your financial resume. It creates a safety net of consistency. If you spend six months making on-time payments, you want that gold star to appear on every record possible. This consistency is what builds the "thick" credit file that high-level lenders look for when approving premium rewards cards or low-interest home loans.
Secured Cards: The Reliability Leaders
For most people starting from scratch or rebuilding after a bankruptcy, secured credit cards are the most reliable path. These cards require a security deposit—usually starting around $200—which typically serves as your credit limit. Because the bank has your deposit as collateral, they are far more likely to approve you even with a poor score.
How Secured Reporting Works
The magic of a quality secured card is that it functions exactly like a "real" credit card in the eyes of the bureaus. When you use the card to buy groceries and then pay the bill at the end of the month, the bank sends a data file to Equifax, Experian, and TransUnion. They don't usually label the account as "secured" in a way that hurts your score; they simply report a revolving line of credit with a perfect payment history.
Graduation and Deposit Returns
The best secured cards offer a path to graduation. This means that after a certain period of responsible use—often six to twelve months—the bank reviews your account. If you have been consistent, they may return your security deposit and convert the account into a standard unsecured card. This is a major win because it allows you to keep the age of the account active, which is a significant factor in your overall credit score.
Unsecured Cards for Limited History
If you prefer not to tie up your cash in a security deposit, there are unsecured cards designed for people with "fair" or limited credit. These cards often use alternative data, such as your bank account cash flow or employment history, to determine eligibility. However, you must be careful. The unsecured market for low-credit borrowers is often filled with "fee-harvesting" cards.
Avoiding the Fee Trap
Some cards targeted at those with poor credit charge massive setup fees, monthly maintenance fees, and high annual fees. You might find yourself with a $300 limit but only $225 of usable credit because $75 was immediately taken for fees. Always prioritize cards that report to all three bureaus but keep their fee structure transparent. If a card charges you just for the privilege of opening the account, it might be better to put that money into a refundable deposit for a secured card instead.
The Role of Retail and Store Cards
Many people think a store card is an easy way to build credit. While some store cards do report to all three bureaus, many only report to one. Furthermore, store cards often have very low limits and high interest rates. If you spend $100 on a card with a $200 limit, your credit utilization is 50%, which can actually hurt your score. If you go the retail route, verify their reporting practices first and keep your spending very low.
Strategic Use to Accelerate Growth
Simply owning the card is not enough. To see your score climb, you need to manage the card with precision. The two most important factors are payment history and credit utilization. Payment history is simple: never, ever be late. Even one payment that is 30 days late can tank a score you have spent months building.
Credit utilization is slightly more nuanced. This is the percentage of your total credit limit that you are using. For example, if your limit is $500 and your balance is $250, your utilization is 50%. Experts generally recommend keeping this under 30%, but for the fastest credit building, keeping it under 10% is even better. You don't need to carry a balance or pay interest to build credit. Paying your statement in full every month shows the bureaus that you are a responsible borrower who doesn't rely too heavily on debt.
Common Pitfalls to Watch For
One common mistake is applying for too many cards at once. Each application usually triggers a "hard inquiry" on your credit report, which can cause a temporary dip in your score. If you apply for five cards in one week, lenders might see you as desperate for credit, which signals risk. Space out your applications and only apply for cards where you meet the basic eligibility criteria.
Another pitfall is closing your oldest account once your score improves. The length of your credit history matters. If you started with a secured card that reports to all three bureaus, try to keep that account open even after you get better cards. If the card has no annual fee, there is no harm in keeping it active with a small subscription or occasional purchase to ensure the account continues to age and contribute to your score.
Frequently Asked Questions
How long does it take for a new card to show up on my credit report?
Most credit card issuers report to the bureaus once a month, typically at the end of your billing cycle. It can take anywhere from 30 to 60 days for a new account to appear on all three of your credit reports. If you don't see it after two months, contact the issuer to ensure they have your correct information.
Can I build credit if I only use the card for one small purchase a month?
Yes. In fact, this is one of the most effective ways to build credit. The bureaus don't care if you spend $5 or $500; they care that you have an active account and that you paid the bill on time. Using the card for a single small monthly subscription and setting up auto-pay is a great "set it and forget it" strategy.
Do all secured cards report to all three bureaus?
No, not all of them do. Some smaller banks or credit unions might only report to one or two. Before you apply and put down a deposit, always check the card's terms and conditions or ask customer service directly if they report to Equifax, Experian, and TransUnion.
What happens to my score if I close a credit building card?
Closing an account can decrease the average age of your credit history and reduce your total available credit, which might cause your score to drop. If the card has no annual fee, it is usually better to keep it open. If you must close it, ensure you have other active accounts that report to all three bureaus to maintain your momentum.
Is there a minimum credit score needed for a secured card?
Most secured cards do not have a strict minimum credit score. Many are specifically designed for people with scores in the "poor" range (below 580) or those with no score at all. The security deposit acts as the bank's protection, making them much more lenient with approvals.
Conclusion
Building credit is a marathon, not a sprint, but using the right equipment makes the race much easier. By focusing on credit building cards that report to all major bureaus, you ensure that every on-time payment and every bit of responsible management is working triple-time for you. Avoid cards with predatory fees, keep your utilization low, and be patient. Over time, these small, consistent actions will open doors to better financial opportunities, from lower insurance premiums to the keys to a new home.